I spent parts of September getting even deeper into the sales side of Matyx, our water treatment digital marketing agency. I wanted to get a better handle of what wasn’t working (just a couple wins over 4 months vs. an average of 3-4 wins/month when we acquired the business), so I inserted myself into the org, something that required a deeper convo with our CEO Justyn, who, while appreciative of the support was also concerned about how things would play out.
I ended up spending most of my time on the sales/rev ops side, helping the team with generating prospecting lists (Claude + Monid has been fantastic for enriched lists) and building a custom connector between our CRM and their sales dialer software. I’d like to think that it’s been helpful. The goal is to have our sales team spend the majority of their time making phone calls and pitching deals vs. trying to enrich contacts and find leads themselves. The connector, if we can get it working 100%, will also make CRM updates a cinch vs. a manual CSV import and export each day. Also, having a simply Slack alert that shows how many dials each rep had the previous day has already brought way more transparency into the agency’s inputs (i.e. more calls = more potential opportunities).
While I’d much prefer focusing on deals and prepping for our upcoming Q4 board meetings, the Matyx experience has been valuable. It’s allowed me to get to know the sales team better and to get a stronger handle on the go-to-market motion that we’re executing. My takeaway was that we have a lot of infrastructure still yet to build (e.g. sales materials, better proposals, documented processes, better marketing support, clearer services offering, etc.). And yes, I have thought about hiring more capable and more experienced rev ops folks (agencies or consultants) to come and help with this, but I felt it was necessary for me to get more hands-on to gain greater understanding of the business. Still a possibility in the future.
Financially, it looks like the agency will do moderately better this month, not because of anything I did, but because the founder/seller got wind of our struggles and decided to help us drum up some business, sending some leads our way. They’re mostly one-off website projects that aren’t exactly our ICP, but with debt service payments and investors on the cap table, we’ll gladly take the short-term revenue to buy more time to get our sales engine right.
About Agency Journey: This is a monthly series detailing the happenings at Barrel Holdings, a portfolio of agency businesses. You can find previous episodes here.
Highlights
My Talk on Client Experience vs. Quality Work
A few months ago, Jerred Hurst, founder of Primitive, a digital agency based in Lubbock, TX, invited me to give a virtual talk to his agency after he read my blog post on Client Experience vs. Quality Work. I finally gave the talk in September, and it was fun to take a blog post I had written 5+ years ago and turn it into a fleshed out 30-min presentation.
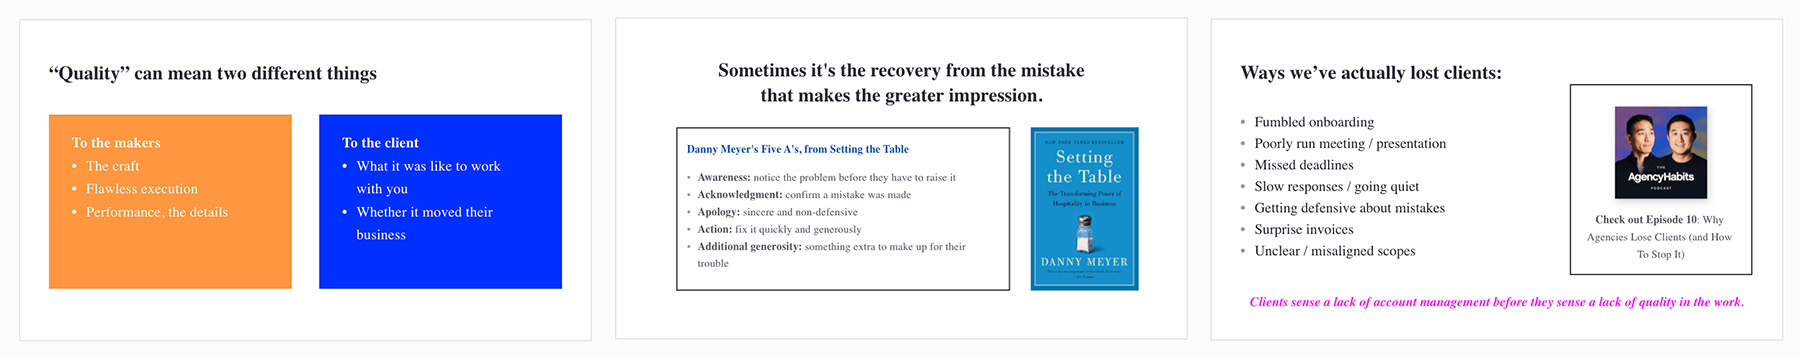
Some slides from my talk on client experience vs. quality work.
The main point I make is through a restaurant analogy: the food at a restaurant might be great (quality work), but if the staff is rude or the bathroom is dirty or the bill has a mistake on it, it’s possible your overall impression of the restaurant could be ruined. In the agency model, client experience is the key way many clients judge the quality of the agency. Slow responses, poorly-run meetings, surprise invoices, and lack of project management–these are all things that will leave a sour taste in the clients’ mouth even if the work is, in the agency’s view, “great”.
Of course, it’s not about choosing client experience over quality work and emphasizing one over the other, but recognizing that both are very important, and the best agencies deliver quality work while also providing their clients with world-class hospitality-type experience.
If you want to check out slides from the talk, here’s the link.
Quick Updates from Across the Portfolio
Aside from Matyx, which has consumed the lion share of my personal attention, the rest of the portfolio has been experiencing its ups and downs. Some brief notes:
- BX Studio had an incredible Q3, its best ever, posting record levels of revenue and profit driven by strong website project sales and ongoing optimization engagements. At a time when some people have questioned Webflow’s staying power in the face of AI, BX has continued to win new Webflow projects with some notable clients.
- Barrel’s Q3 was a mixed bag: some great new additions to the team that will help in the long run, some challenging client engagements especially on the engineering side that they’ve been cleaning up, and a couple legal issues that popped up. Barrel had some nice new logo wins, but lots of work to do in terms of securing 2027 deals in Q4.
- Prima Mode has been ramping up top of funnel marketing activities with webinars, meetups, sponsorships, and dinners. Their largest client unfortunately gave notice (they brought on new investors, are trying to sell, and needed to cut costs even though Prima Mode delivered really excellent Amazon performance), so there’s urgency to land some new logos in the coming months.
- AO2 had a heavy quarter of events and lead gen. MRR has been steadily growing though it’ll take a few more deals to get to where we had projected in early 2026. They’re trying to strengthen their TikTok Shop offering, especially around creator management services, something they’re recruiting for.
- Vaulted Oak has been holding steady and posting consistent results. Account Director David Ries, who played a big part in VO’s partnerships motion, recently departed. Co-founder Jason Fan is taking back these responsibilities and continuing to add new talent to the team.
In August, we did post our highest revenue and EBITDA totals across the portfolio, which was cool to see. But before we could dream about such a run rate (basically multiplying the month’s results by 12 and posing like this was our new revenue/EBITDA), a closer look revealed that there was a good amount of project-based/one-time revenue in there that will most likely come down in September. Looking at the pipelines across the portfolio, though, it’s possible that we can exceed the all-time high with some key new logo wins and strong retention of existing accounts.
Top of Mind
Exploring a Fund and Why We’re Not Raising One
I spent some time in September exploring the possibility of raising a fund. What would it look like to raise capital, what would our pitch be, and how might it play out? I had Brandon, our head of M&A at Barrel Holdings, model out a bunch of scenarios. With Brandon and Sei-Wook, we had some good conversations about the pros and cons of going the fund model.
The exercise came about because in my conversations with agency founders, I sometimes wondered about a different investment approach: instead of a full buyout like we’ve done with our deals to date, what if we took a minority investment in a small but fast-growing agency or had the founder roll over a significant amount of equity (30-40%)? In either case, we wouldn’t be able to leverage the SBA 7(a) loan, so in my mind, a fund could be one way to achieve this approach. Raising on a deal-by-deal basis is the other alternative, but I wanted to see if there was a fund model that made sense.
The fund I had in mind was something akin to Permanent Equity, the private equity group in Columbia, Missouri, that buys cash-flowing family-owned businesses with little to no leverage and a very long time horizon (25+ years). I found what I could on their model (no fees on money raised, upside on cash distributions, types of acquisitions) and we tried some of our variables that felt good.
Using a 20-year fund life, we ran some scenarios and outcomes. Looking at the model, it was possible to get good results for the LPs with a handful of very strong investments, but the more we talked about it, the more we came back to a deeper question: why?
Is it worth it to go down this path and take on different types of obligations in order to speed up our ability to make some different types of investments? Would I enjoy deploying capital on a schedule vs. being maximally flexible? And how would we explain the existing Barrel Holdings portfolio? Would it somehow be “invested” into the fund as our own GP stake, or would we keep it separate and say we’d offer the existing holdco support to the companies in the fund for a fee?
And what of the original vision of building a permanent capital holdco? The idea that our portfolio of cash-flowing businesses would get to a scale large enough to easily fund the next acquisition with little to no debt and keep the flywheel growing?
The more we explored the fund model, the more we realized that we wanted to stick with the original holdco approach. What it would take is something I often lack: patience. We talked about how, if we can get to a certain level of EBITDA through organic growth and a couple more acquisitions using SBA, probably 3-4x where we are today, and demonstrate solid free cash flow along with a more built-out holdco support motion, we might be able to raise some significant capital at the holdco level by issuing shares to potential investors (nothing crazy, maybe 10-20% of the company). It’d set us on the path of other permanent capital holdcos that have strategically used stock sales to build up their balance sheet and have a war chest to do deals. We could then also do periodic stock buybacks to give investors (as well as future employees and portco leaders) some liquidity now and then.
So the hours spent deliberating on a fund model and its possibilities ultimately led us back to having greater conviction on our current path: keep supporting our existing portfolio, especially in the way we help them grow organically, and look for the next opportunistic acquisition that can add meaningful revenue and EBITDA with room to improve organically. Do this well, and we’ll get to a scale that’ll open up more possibilities.
It’s a model that’ll continue to test my patience, but one that I’m excited to see bear out.
Shared Quotes
“Hindsight bias is the tendency, after an outcome is known, to see the outcome as having been inevitable.” (Annie Duke, Thinking in Bets)
As optimistic as I might have sounded in the last section, I wanted to highlight this quote because, in all honesty, the outcome looks anything but inevitable. Lots of uncertainty with our investment thesis (small specialized agencies), the long-term durability of our businesses, and the likelihood of making good future investments. All we can do is focus on our inputs, learn from our experiences, and survive whatever comes our way.
“As long as we measure others and ourselves by what we have and how we look, life is inevitably a discouraging experience, characterized by greed, envy, and a desire to be someone else.” (Gordon Livingston, Too Soon Old, Too Late Smart)
The other dimension to the “why” question I raised in the previous section: if the goal in life is to build the biggest portfolio possible and amass as much personal wealth as I can in a hurry, then perhaps I owe it to myself to raise as big of a fund as possible and swing for the fences. But I’m not interested in these things being my measures of success. I care about quality time with loved ones, pursuing excellence for its own sake (not for external validation), and serving others through teaching and achieving things together. As for money, I’m sure we’ll make enough along the way.